Chapter 1
What if the largest family offices funded humanity first?
A study of private capital, the world's documented funding gaps, and the causes recorded in the PRIMA Philanthropic Capital Atlas.
Private wealth is concentrated in a small number of family offices. The world's largest documented gaps, in clean energy, nature, housing, water, health and education, are measured in hundreds of billions of dollars a year. This study asks a simple question: if part of that private capital were directed to those gaps first, what could change?
Most family office capital is managed to preserve and grow wealth across generations. That horizon is long, which makes it unusually well suited to problems that take decades to solve. The question is not whether returns matter. It is whether long-horizon capital can be pointed at the causes that matter most while still being stewarded responsibly.
We find that even a modest share would close meaningful parts of several gaps, and that the bottleneck is less the existence of money than the connection between capital and credible, investable work. That connection is what PRIMA is built to make.
Thought experiment built on public estimates. No family office named here has agreed to anything.
Chapter 2
The capital
Private capital, built to last generations. We used the cautious end of each repeatedly published estimate.
Single-family offices rarely disclose assets and no verifiable public top 100 list exists. Most figures are third-party estimates and often describe family wealth rather than office assets.
Chapter 3
The funding gaps
The gaps the world has measured: published estimates of the additional money needed every year.
Chapter 4
Top causes in the Atlas
Documented needs, appeals and recovery costs country by country, each with its source, as of 2026-10-16.
Totals never double count overlapping plans. Ranking uses only quantified need records.
Unmet annual gaps
Money still missing from published appeals and response plans this year.
- 21 records. Largest: Ukraine Humanitarian Needs and Response Plan 2026; Venezuela Regional Refugee and Migrant Response Plan (RMRP) 2026.
- 8 records. Largest: Shelter & Non-Food Items (Ukraine 2026); Sécurité Alimentaire (Haiti 2026).
- 7 records. Largest: Multi-purpose Cash (Ukraine 2026); Integration (Venezuela (RMRP) 2026).
- 27 records. Largest: Protection (Venezuela (RMRP) 2026); Protección (Colombia 2026).
- 7 records. Largest: Agua, saneamiento e higiene (Venezuela 2026); Water, Sanitation & Hygiene (Ukraine 2026).
- 7 records. Largest: Salud (Venezuela 2026); Salud (Colombia 2026).
- 14 records. Largest: Educación (Venezuela 2026); Educación en Emergencias (Colombia 2026).
- 8 records. Largest: Shelter (Venezuela (RMRP) 2026); Abris et BNA (Haiti 2026).
- 11 records. Largest: Common services (Venezuela (RMRP) 2026); Coordinación (Colombia 2026).
- 3 records. Largest: Nutrition (Haiti 2026); Nutrición (Venezuela 2026).
Long-term capital needs
Multi-year reconstruction and infrastructure needs: where patient capital fits best.
- 2 records. Largest: India urban infrastructure investment need to 2036.
- 1 records. Largest: US drinking water infrastructure need (7th DWINSA).
- 3 records. Largest: Ukraine recovery and reconstruction needs (RDNA5); Ukraine direct physical damage (RDNA5).
- 3 records. Largest: First Nations infrastructure gap to 2030; First Nations infrastructure gap: capital plus O&M (parliamentary briefing).
- 10 records. Largest: Venezuela earthquakes: analytical damage estimate (UNDRR); Venezuela June 2026 earthquakes: direct damage (GRADE).
- 9 records. Largest: Hurricane Melissa: direct damage in Jamaica (GRADE); Hurricane Dorian total effects, The Bahamas.
- 1 records. Largest: Blatten 2030 reconstruction (reported estimate).
- 3 records. Largest: Grindavík residential buyout after volcanic eruptions.
Explore the full Atlas at alex.primaapp.com/philanthropy-atlas.
Chapter 5
Simulation
Imagine a share pointed at the gaps. Money is split across areas in proportion to each area's annual gap.
Chapter 6
What it could achieve
At 10% of the estimated capital, published cost per result suggests:
Costs rise as the easiest wins are taken, so very large sums would likely achieve less per dollar than shown.
Chapter 7
Patient capital
Capital that waits for things to grow. Grants alone cannot close gaps of this size.
Much of the work, clean energy, water systems, housing, food and health technology, can be built by companies that earn revenue while doing good. What they need is capital that accepts longer timelines and measures success in outcomes as well as returns.
Family offices, wealth offices and fund managers with long horizons are natural providers of that capital. The challenge is discovery: finding credible founders whose work fits a stated mandate, without months of events and unstructured decks.
Chapter 8
The PRIMA philanthropy model
The biggest advantage: finally, philanthropic dollars can be magnified instead of spent once.
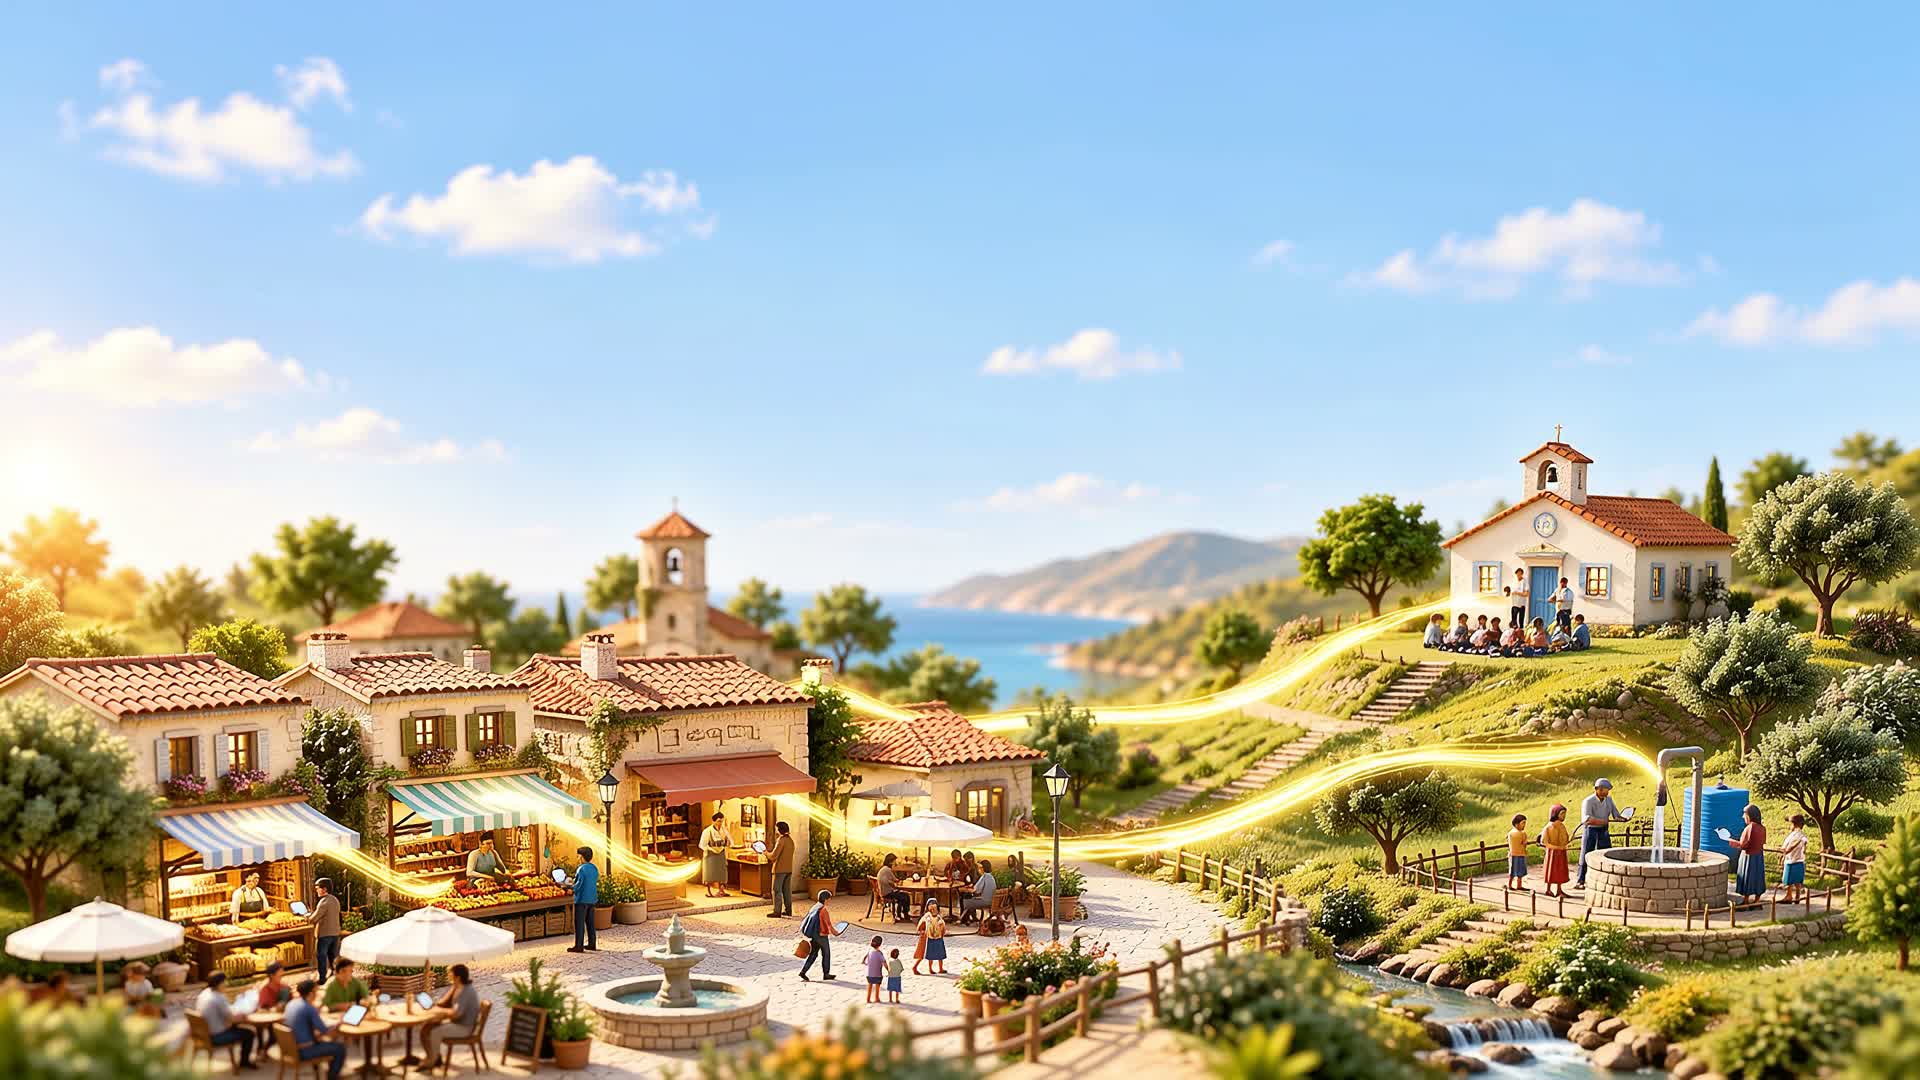
Through PRIMA's philanthropy model, philanthropic capital is used to hire local people who bring their markets onto PRIMA. Digitizing those economies creates far more value for every participant, and the excess profits are intended to flow back into philanthropic projects around the world.
- Fund local teamsPhilanthropic capital hires people in the communities it aims to lift.
- Onboard marketsThose teams bring local businesses, providers and recommenders onto PRIMA.
- Digitize the economyBusinesses fill unused capacity, recommenders earn on completed bookings, customers find trusted services.
- Return the surplusExcess profits are funneled back to philanthropic projects worldwide, funding the next round.
That is why it multiplies: one gift creates jobs, then a working digital economy, then recurring surplus that can be given again. This describes PRIMA's intended model and policy aspiration. Surplus is shared after agreed costs and distributions, and no returns or amounts are promised.
Chapter 9
What if 10% pointed at PRIMA?
One tenth of the largest family offices' capital, pointed at bringing PRIMA to every country.
Instead of being spent once, that capital could fund local teams who onboard each country's businesses, providers and recommenders. Every market they open starts producing booking fees from capacity that would otherwise go unused: empty tables, unsold rooms, open appointment slots.
The next chapter shows what a country could generate when only a small share of its people use PRIMA.
Chapter 10
What each country could generate
Yearly booking fees if a share of each population used PRIMA, at 3 completed bookings a day and $5 per booking.
- 34.0 million people. Half, $93 billion, goes to the recommenders who brought the bookings.
- 140.9 million people. Half, $386 billion, goes to the recommenders who brought the bookings.
- 145.1 million people. Half, $397 billion, goes to the recommenders who brought the bookings.
- 8.4 million people. Half, $23 billion, goes to the recommenders who brought the bookings.
- 12.4 million people. Half, $34 billion, goes to the recommenders who brought the bookings.
- 6.9 million people. Half, $19 billion, goes to the recommenders who brought the bookings.
- 6.9 million people. Half, $19 billion, goes to the recommenders who brought the bookings.
- 5.9 million people. Half, $16 billion, goes to the recommenders who brought the bookings.
- 4.1 million people. Half, $11 billion, goes to the recommenders who brought the bookings.
Model from Digital Alex's national income study, population from the World Bank (2024), as of 21 October 2026. An illustration of scale, not a forecast. Source
Chapter 11
Incremental, so it keeps multiplying
This value is new. It comes from capacity that would otherwise expire, so it adds to the economy instead of taking from it.
Because the bookings fill seats, rooms and hours that would have gone empty, the fees do not replace existing spending. That is what makes the surplus available for good: after agreed costs and distributions, it can be pointed at philanthropic projects.
And it does not stop. Those projects fund the next teams, who open the next markets, which generate the next surplus. One gift becomes a cycle.
- FundFamily office capital hires local teams.
- OnboardTeams bring each market onto PRIMA.
- EarnUnused capacity becomes completed bookings.
- GiveSurplus flows to philanthropic projects.
- ExpandThe next country starts, and the cycle repeats.
This describes PRIMA's intended model and policy aspiration. Figures are illustrative, no returns or amounts are promised, and income is not guaranteed.
Chapter 12
How PRIMA matches
Founders and capital meet only when both say yes.
- Founders share their work. Impact and sustainable companies answer a few questions, upload decks privately and record a short voice pitch.
- Investors state their mandate. Wealth offices and fund managers choose the industries, causes, stages and ticket sizes they fund.
- Matches appear. PRIMA shows where a founder's industries and stage fit an investor's mandate.
- Both say yes. An investor requests an intro; decks become visible only after the founder accepts.
Impact industries available: Pharmaceuticals, Biotechnology, Medical Devices, Healthcare Services, Global Health, Mental Health and Wellness, Renewable Energy, Energy Storage and Grid, Carbon Removal, Climate Adaptation, Agriculture, Food and Agtech, Water and Sanitation, Oceans and Biodiversity, Education, Education Technology, Financial Inclusion, Electric Mobility, Affordable Housing, Infrastructure, Recycling and Circular Economy.
Chapter 13
Limits of this study
What these numbers can and cannot tell you.
- Family office figures are third-party estimates and often describe family wealth, not investable office assets.
- Funding gaps come from different institutions and years and are not perfectly additive.
- Atlas rankings reflect what has been documented and quantified so far, not a complete list of the world's needs.
- A match on PRIMA is an introduction, not an investment commitment. No returns or funding are guaranteed.
Chapter 14
The marketplace
Founders and capital, meeting halfway. Choose your side to begin.
15. Sources
All figures and where they come from
- PRIMA Philanthropic Capital Atlas, snapshot 2026-10-16. Source
- Clean energy in developing countries: UNCTAD: $1.7tn a year needed. Source
- Nature and biodiversity: Paulson Institute: $711bn to $942bn a year. Source
- Affordable housing: McKinsey Global Institute: $650bn a year. Source
- Climate adaptation: UNEP: $194bn to $366bn a year. Source
- Ocean protection: Marine Policy 2020: $149bn a year. Source
- Clean water and sanitation: World Bank: $112bn a year for SDG 6.1 and 6.2. Source
- Education: UNESCO: $97bn a year. Source
- Ending hunger: Food Policy 2021: $33bn to $39bn a year. Source
- Electricity access in Africa: IEA: $15bn a year to 2035. Source
- Tuberculosis: WHO: $13bn spent vs $22bn target. Source
- Malaria: WHO: $7.3bn needed, about half funded. Source
- Lives saved from malaria: GiveWell top charities: $3,000 to $5,500 per life at today's margin. Source
- Tonnes of CO2 avoided: IPCC AR6: many clean energy options at $20 to $100 per tonne. Source
- Hectares of land restored: Verhoeven et al. 2024: $185 to $3,012 per hectare. Source
- People given electricity: IEA: $150bn for about 600 million people, about $250 each (derived). Source
- Excession (Musk), USA: $200bn (published range 200 to 650), 2026, low confidence. Source
- Walton Enterprises, USA: $200bn (published range 200 to 300), 2026, med confidence. Source
- Agache (Arnault), France: $200bn, 2026, low confidence. Source
- Ellison Revocable Trust, USA: $150bn, 2026, low confidence. Source
- Mars Family Office, USA: $141bn, 2026, low confidence. Source
- Pontegadea (Ortega), Spain: $124bn (published range EUR 117bn total assets), 2025, high confidence. Source
- Ambani Family Office, India: $100bn, 2026, low confidence. Source
- Dumas Family Office (Hermes), France: $100bn, 2026, low confidence. Source
- Bayshore Global (Brin), USA: $90bn (published range 90 to 239), 2026, low confidence. Source
- Tethys Invest (Bettencourt Meyers), France: $90bn, 2026, low confidence. Source
- Mousse Partners (Wertheimer), USA / France: $90bn, 2026, low confidence. Source
- Grupo Carso (Slim), Mexico: $80bn, 2026, low confidence. Source
- Cascade Investment (Gates), USA: $70bn (published range 70 to 230), 2026, med confidence. Source
- Delfin (Del Vecchio), Luxembourg: $60.5bn, 2026, low confidence. Source
- Fedesa (Ferrero), Monaco: $55bn, 2026, low confidence. Source
- MSD Capital (Dell), USA: $50bn, 2026, low confidence. Source
- S.B. Adani Family Trust, India: $50bn, 2026, low confidence. Source
- Athos (Struengmann), Germany: $30bn, 2026, low confidence. Source
- Horizons Ventures (Li Ka-shing), Hong Kong: $30bn, 2026, low confidence. Source
- Hillspire (Schmidt), USA: $25bn, 2026, low confidence. Source
- KIRKBI (LEGO), Denmark: $25bn, 2026, med confidence. Source
- Mobilis (Mulliez), France: $25bn, 2026, low confidence. Source